The Basics
What Is Your Hail Deductible?
Your deductible is the amount you agreed to pay out of pocket before your comprehensive insurance coverage kicks in on a claim. It’s set when you choose your policy, and it typically ranges from a few hundred to around a thousand dollars depending on the coverage you selected. On a hail claim, your insurer covers the approved repair cost above your deductible, which is why a severe hail repair totaling several thousand dollars can still cost you only your deductible amount out of pocket. The deductible isn’t a fee a shop charges you; it’s a term of your contract with your insurance company, which is an important distinction when you start hearing claims about deductibles being waived or covered by a repair shop. Some policies also carry a separate, often lower, deductible specifically for comprehensive claims like hail compared to collision claims, so it’s worth confirming which figure actually applies to your situation rather than assuming your collision deductible is the relevant number.
How Deductibles Are Sometimes Misrepresented
Common Deductible Myths Worth Knowing
A few misconceptions come up often enough that they’re worth addressing directly. One is the idea that if a shop doesn’t ask you for the deductible amount, it simply disappears from the transaction; in reality, someone is still accounting for that amount somewhere, whether through pricing structure or estimate handling, and it’s worth understanding how. Another is the assumption that every “no deductible” offer works the same way, when in practice the mechanics behind similar-sounding promises can differ significantly between shops. A third is thinking that asking a shop to explain their deductible handling is somehow rude or unnecessary; it’s a completely reasonable question, and a legitimate shop should be able to answer it clearly and specifically rather than deflecting to a general marketing line.
The Gray Area
What Does "$0 Out of Pocket" Actually Mean?
When a shop advertises “$0 out of pocket” or “no deductible,” they’re typically referring to one of a few different things, and it’s worth understanding which one you’re actually being offered. Some shops build the deductible amount into their overall pricing structure in a way that’s transparent and disclosed upfront. Others may inflate the repair estimate submitted to your insurer to effectively cover the deductible, which can raise legal and insurance fraud concerns depending on how it’s structured, since misrepresenting repair costs to an insurer is a serious issue regardless of intent. Colorado has specific rules around how deductibles can and cannot be handled by repair shops, and the details matter more than the marketing phrase. If a shop can’t clearly explain exactly how their “no deductible” offer works, that’s a reasonable signal to ask more questions or get a second opinion before committing. This isn’t a reason to avoid every shop that mentions deductible assistance; it’s a reason to ask specifically how it works before assuming the phrase means the same thing everywhere you hear it.
What We Actually Do
How Our Pricing Works
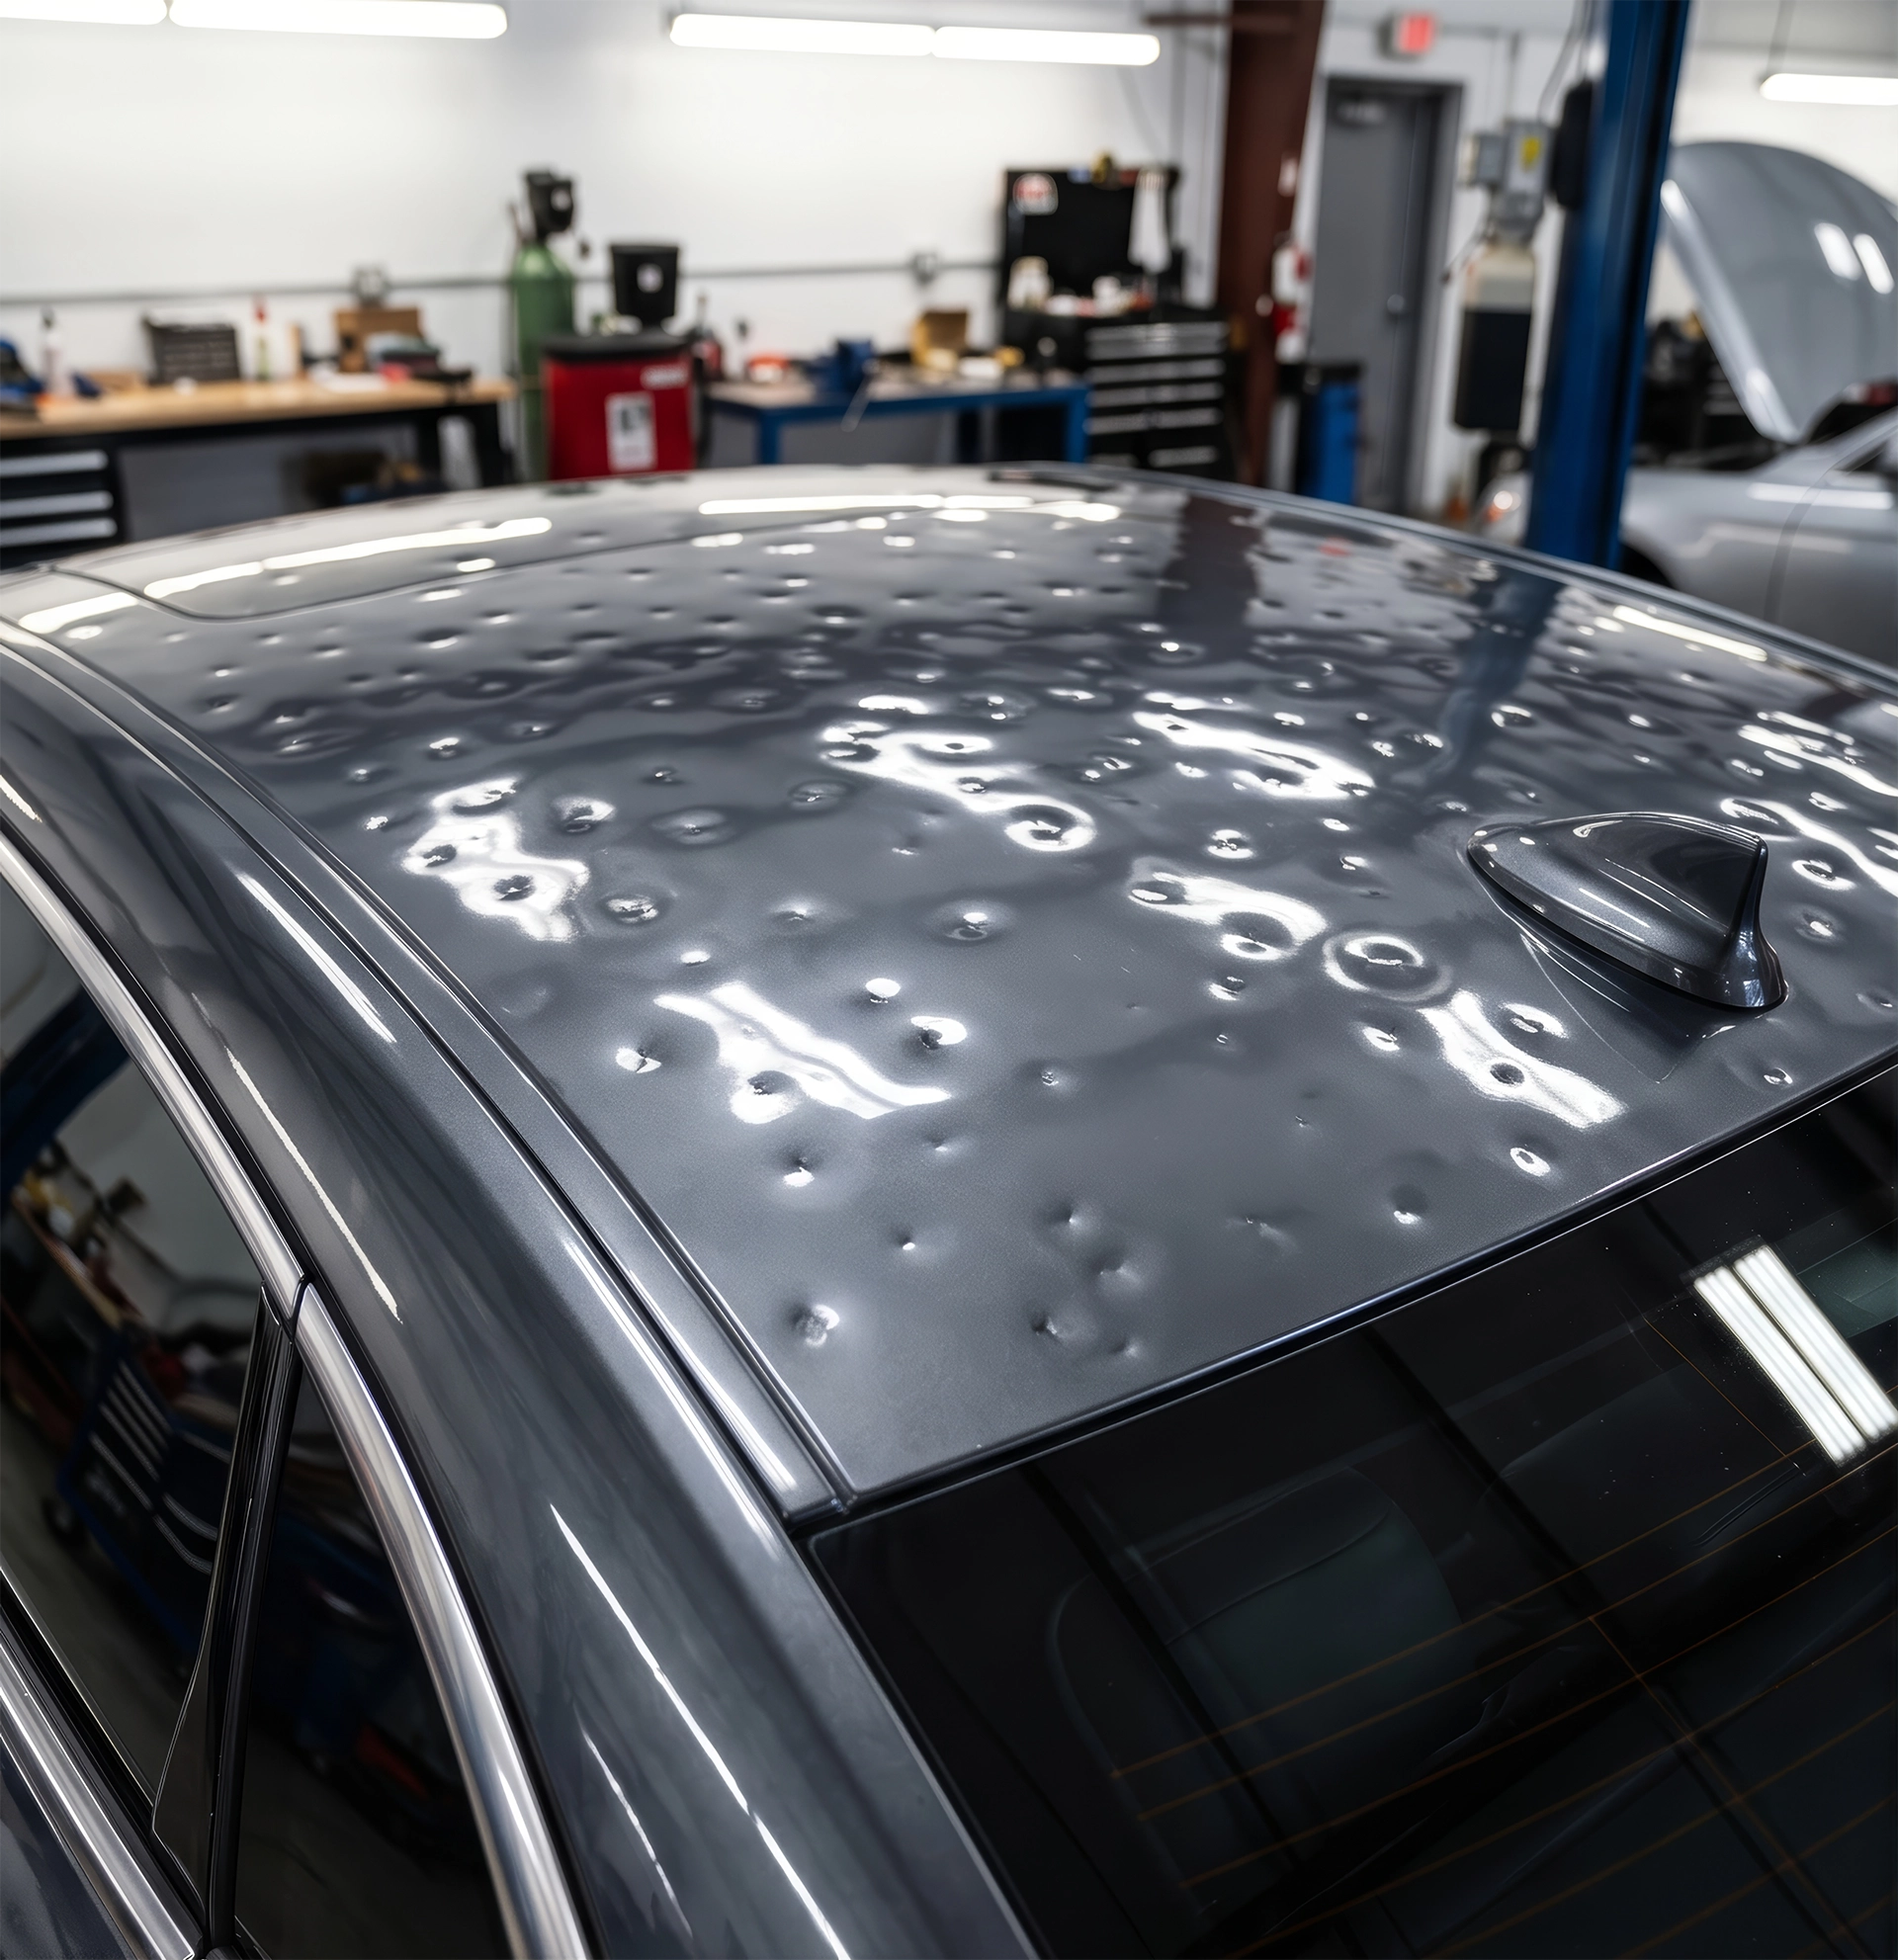
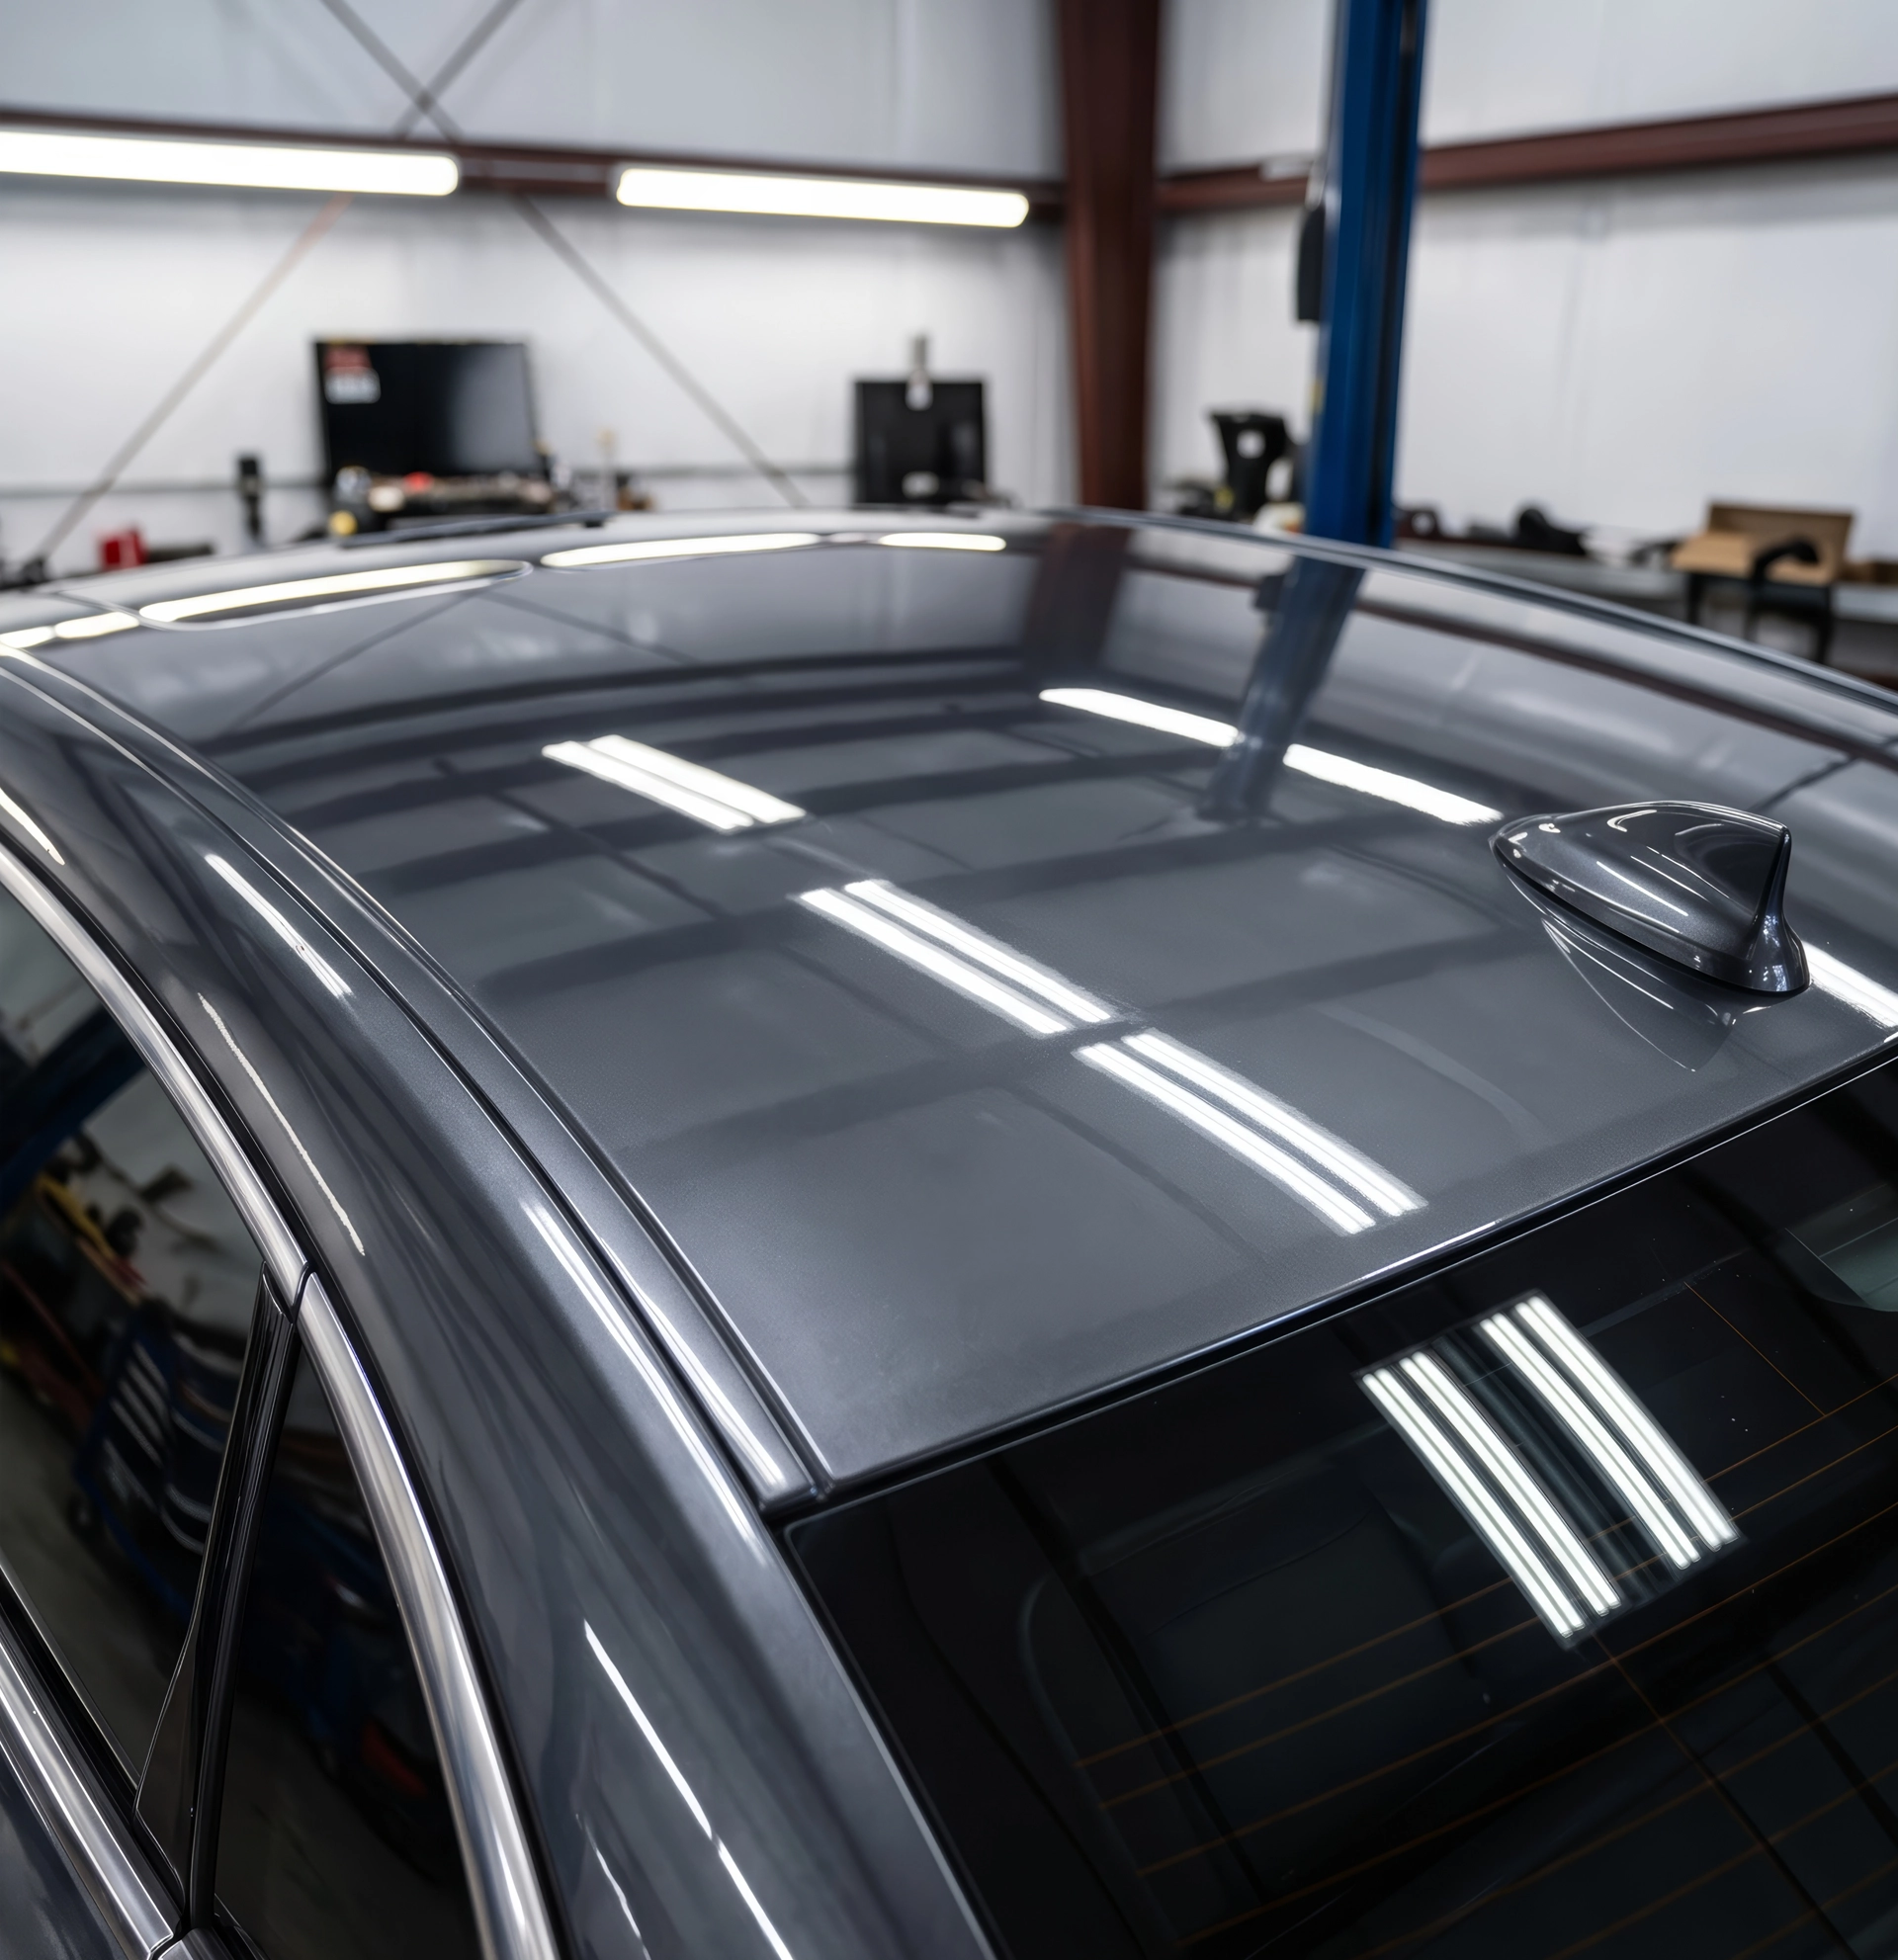
We don’t advertise “$0 out of pocket” because we’d rather you understand exactly what you’re paying and why. Your deductible is your deductible, set by your insurance policy, and we bill your carrier for the approved repair amount above it. Our estimates reflect the actual damage we find during inspection, documented panel by panel, submitted to your insurer as an accurate representation of the repair needed, not inflated to offset your deductible. If you’re deciding whether a hail claim is worth filing at all, comparing your deductible to your actual repair estimate, which we provide for free, is the most reliable way to make that decision rather than relying on a shop’s marketing promise. This approach also protects you: an inflated estimate submitted on your behalf can create complications for you personally down the line, even if the shop was the one who structured it, since your name is on the claim.
How It Works
Understanding Your Deductible Before You File
A few simple steps help you understand exactly what you’re dealing with before committing to a claim.
Your Hail Deductible, Explained Honestly
Contact us for a free inspection and an honest read on whether filing a claim makes sense for your deductible.
Why It Matters
Why Deductible Transparency Matters
A shop that’s upfront about how your deductible works, rather than leading with a slogan, is generally a shop that’s confident in the actual quality and pricing of its repair work. Deductible-related promises are one of the easiest ways for a storm-chasing outfit to win a job quickly after a big event, since “no deductible” sounds appealing when you’re staring at a hail-damaged vehicle. But a shop that’s not going to be in Colorado next season has little incentive to worry about whether that promise holds up to scrutiny later. We’d rather earn your business with a repair and a price that holds up, not a marketing line that needs a lot of fine print to actually explain. If you’ve already had a “no deductible” repair done elsewhere and something about the way it was handled doesn’t sit right, it’s worth reviewing your paperwork and confirming with your insurer exactly what was submitted on your behalf.
Coverage Area
Deductible Guidance Across the Denver Metro
We provide the same transparent pricing and deductible guidance throughout Denver and the surrounding Front Range, including Aurora, Lakewood, Arvada, Westminster, Thornton, Centennial, Littleton, Highlands Ranch, Parker, Castle Rock, and Colorado Springs. No matter which city you’re in, the same honest approach to your deductible and your claim applies.
Your Hail Deductible FAQ — Colorado
Is my deductible negotiable with a repair shop?
No. Your deductible is set by your insurance policy, not by the repair shop. A shop can be transparent about how they price around it, but they don’t have the authority to change your policy’s deductible amount.
Is "$0 out of pocket" hail repair legal in Colorado?
It depends entirely on how it’s structured. Some approaches are transparent and legitimate; others involve inflating estimates in ways that raise legal concerns. Ask a shop to explain exactly how their offer works before assuming it’s straightforward.
Do you offer to cover my deductible?
No. We bill accurately for the repair we actually perform and let your deductible work the way your policy defines it, rather than building a workaround into our pricing.
How do I find out my exact deductible amount?
Check your insurance policy declarations page, or call your insurer directly. They can confirm your specific comprehensive deductible in a couple of minutes.
Should I ask a shop how their "no deductible" claim works?
Yes. If a shop can’t clearly explain the mechanics of a deductible-related promise, that’s worth treating as a signal to ask more questions or get a second opinion elsewhere.
Get Started
Get a Real Answer About Your Deductible
If you’re weighing whether a hail claim is worth filing, or you’ve heard a “no deductible” promise you want a second opinion on, contact us. We’ll give you a real repair estimate and an honest explanation of how your deductible actually factors in.